How we work
No sales pitch, no pressure to decide on the spot. Here’s exactly what working with us looks like, from the first conversation on.
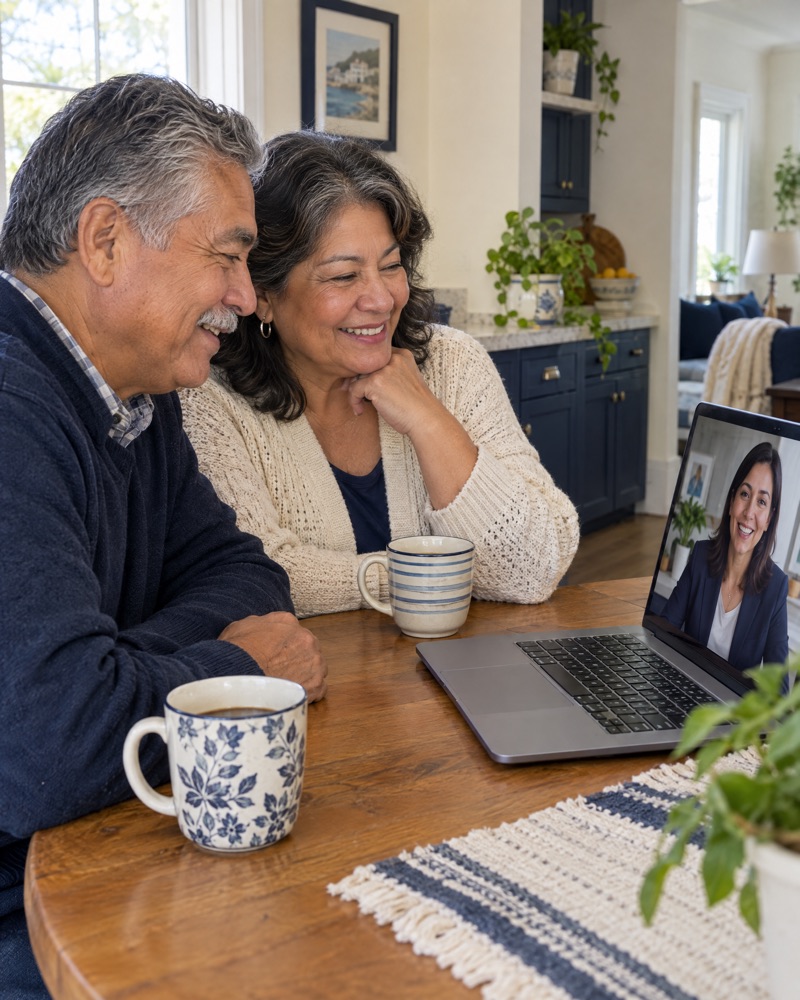
From your kitchen table
Registered to serve clients virtually across all 50 states — no office visit required for any of the four steps above.
How we’re paid
As a fiduciary, we’re legally required to act in your best interest and to be clear with you about how we’re compensated. We believe that’s a diligence question every client deserves a straight answer to — not a detail to bury.
Depending on the service, compensation may come from an advisory fee on assets we manage, or from the insurance carrier on any annuity or insurance product we help you evaluate. We’ll always tell you plainly, before you decide on anything, exactly how we’re paid on that specific recommendation.
Asset Lift's Investment Adviser Representatives are also separately licensed insurance producers and may receive commissions on insurance products — a conflict disclosed and managed under their fiduciary duty as Investment Adviser Representatives; on insurance and annuity recommendations, Texas law requires them to act in your best interest, and Asset Lift holds its representatives to that same fiduciary-level standard as a matter of practice.
We are not owned by, and do not answer to, any insurance company, bank, or brokerage firm. That independence is what lets our recommendations stay about your plan — not a parent company’s product lineup.
Common questions
Not to have the conversation. We start with a plan — any recommendations about where accounts should sit come after, and only where they genuinely help.
Yes. It’s a conversation to understand your situation and see if there’s a fit — not a pitch meeting.
Then you walk away with more clarity than you had before, at no cost. Plenty of people do exactly that.
Yes — we’re registered to serve clients virtually across all 50 states.